Checked 12 October 2026. A loan can feel finished to you while its CIBIL entry still says “settled”. The next step is to compare the repayment arrangement and the credit-report fields, rather than assume a closure letter will remove all past history.
Quick answer: CIBIL distinguishes a loan settled for less than the full payable amount from a loan repaid in full and reported closed. If you want an entry corrected, ask the reporting lender to confirm the repayment position and reporting treatment in writing. CIBIL cannot independently rewrite accurate lender records simply because you prefer a different status.
Settled vs closed in CIBIL: what do the words mean?
CIBIL's own explanation describes a settlement where the borrower paid an agreed amount below the full amount payable. It contrasts that with full repayment reported as closed, and explains why lenders may view a settled record unfavourably. This is a reporting distinction, not a guarantee that every settled borrower will be refused credit. CIBIL's settled-status explanation.
| Status or evidence | What to establish | What not to assume |
|---|---|---|
| Settled | Was the agreed payment below the full payable amount? | That it is identical to full repayment. |
| Closed | Do the balance, closure date and other fields match the lender's records? | That past late-payment history disappeared. |
| NOC or closure letter | What arrangement and account does the wording actually confirm? | That its title alone determines every credit-report field. |
| Written-off or post-write-off status | Ask the lender to explain the exact entry and repayment position. | That it means the same thing as a normally repaid loan. |
Read the complete entry. A zero current balance, a closed date and a status label answer different questions. Compare them with the signed arrangement and final account statement. If you are unsure what a field means, request the lender's explanation before making another payment.
An example: why a settlement receipt is not full-repayment proof
Imagine a lender statement shows ₹80,000 payable and the lender agrees in writing to accept ₹55,000 under a settlement arrangement. The difference is ₹25,000. That arithmetic does not prove ₹25,000 remains legally payable under the arrangement, nor does it tell you what would now be required to change the reporting treatment.
If you later want to explore full-repayment treatment, do not simply transfer that difference to an old payment link. Ask for the current authorised amount, its validity date, how it will be applied and what the lender will report after receiving it. Charges, contractual terms, account ownership or other facts can matter. Get clarification from the lender; independent professional advice may be appropriate if there is a dispute about the agreement.
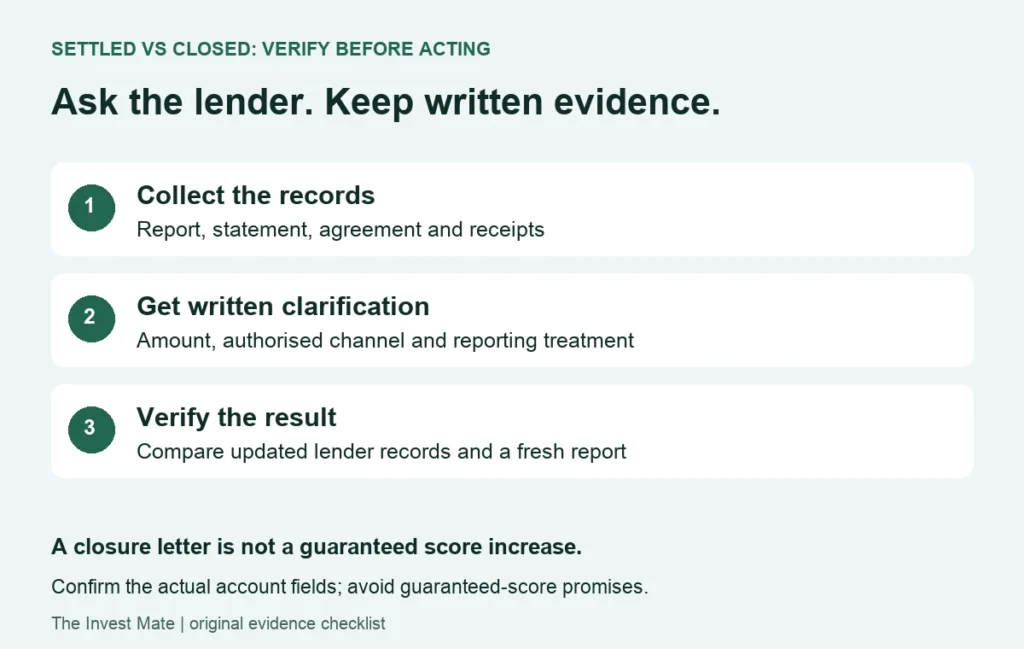
Report, statement, settlement terms and receipts.
Written amount, authorised channel and reporting treatment.
Updated lender records and a fresh credit report.
Can you change settled status to closed?
For your account, request the lender's written position before making another payment. The checklist below organises the questions; it does not establish a right to change a correctly reported status.
Use this checklist to make the discussion concrete:
| Ask for | Why it matters |
|---|---|
| Current written amount and validity date | A historical difference may not equal the amount the lender now accepts. |
| Account reference and authorised payment route | The payment must be attributable to the correct account. |
| Payment allocation and resulting balance | You need a clear reconciliation rather than a verbal assurance. |
| Reporting treatment after payment | Ask which account fields will be updated and on what basis. |
| Final statement and confirmation | Keep evidence for comparing the next report. |
A third-party agent's promise of “750 score in 30 days” is not the lender's confirmation. No one can infer your future score from this status field alone. Do not sign or pay solely because an intermediary claims a guaranteed credit outcome.
I already paid in full, but CIBIL still says settled
First distinguish a stale snapshot from a genuinely wrong entry. Record the report-generation date, the account's reported date and the date the lender posted your payment. Then compare the specific status and balance. Our current RBI credit-report update guide explains the reporting schedule without promising a score-change date.
- Obtain the lender statement or confirmation that supports your claim.
- Highlight the exact disputed fields on a copy of your report.
- Send a factual correction request through the lender's or bureau's official channel.
- Save the acknowledgement and complaint reference.
- Compare the response and any corrected report with your evidence.
CIBIL's dispute guidance explains that the bureau checks disputed information with the relevant credit institution. Correctly closed accounts can remain as credit history. Asking for accurate information is different from asking that an accurate historical account be erased. CIBIL dispute guidance.
A message to request written clarification
Adapt this original template to your facts. Send it yourself through an official lender channel; attach only the relevant documents requested there.
Subject: Clarification of settled account and credit-report status
My report generated on [date] shows [status/balance] for account [reference, masked as appropriate]. My payment/settlement records dated [date] show [brief factual description]. Please confirm the current repayment position and explain the status information submitted to the credit bureau.
If an additional payment arrangement is available, please provide the authorised amount, validity date, payment channel, allocation and reporting treatment in writing. Please also identify the confirmation or final statement I would receive. I am not authorising a payment or new arrangement through this message.
If the existing entry is inaccurate, please register a correction complaint, provide its reference and explain the action taken or reasons for rejecting it. My previous complaint reference is [reference, if any].
Keep a log with the date, channel, reference, response and documents received. Do not post your complete credit report, PAN, OTP or full account number in public comments. This website does not accept repayments or change bureau records.
How long will correction or score recovery take?
There are separate events: the lender confirms an arrangement, a payment posts, account data is reported, a dispute is resolved and the wider credit profile is assessed. Do not turn a case-study correction period into a guaranteed score-recovery deadline.
CIBIL cannot change lender-supplied records on its own; its official FAQ describes checking disputes with the reporting institution. A status correction does not by itself establish what happens to every historical payment entry or your future score. CIBIL's official report and correction FAQ.
If a correction complaint is delayed, check the applicable complaint framework and its eligibility. Our CIBIL dispute guide covers evidence and tracking. If your report is accurate and you want healthier credit habits, use our CIBIL improvement guide; it does not promise a fixed point increase.
Frequently asked questions
Does an NOC guarantee removal of settled status?
No automatic outcome follows from the document's title. Read what it confirms and ask the reporting lender about the specific status and balance fields.
Can a settled loan still affect a future application?
Lenders can consider the account history alongside other information and their lending criteria. A particular approval or rejection cannot be predicted from this guide.
Should I wait a fixed number of years instead of checking the entry?
Do not rely on a universal online deletion claim. Check the actual report and address supported inaccuracies through the official process.
Can I pay an agent to erase accurate credit history?
An agent does not control lender reporting or bureau records. Request evidence and verify claims with the relevant institution; avoid guaranteed-score promises.
What if the lender rejects my correction request?
Read the reasons, compare them with your documents and use its official grievance route if appropriate. Check eligibility before escalating to another forum.
Sources and scope
References checked 12 October 2026: CIBIL's settled-status explanation, CIBIL dispute process and official report FAQ. The ₹80,000/₹55,000 example and message template are original illustrations. This guide does not interpret your contract, direct a financial transaction, guarantee a status change or provide personalised legal/financial advice.


