Checked 11 October 2026. This guide covers Indian UPI payment problems and links to official support. No account details are collected here.
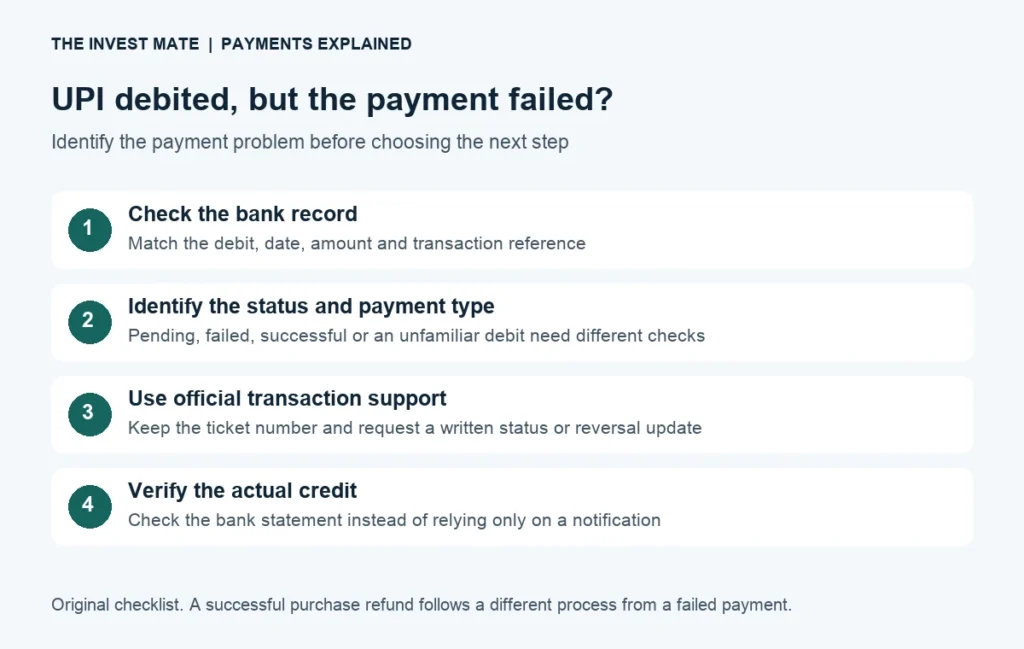
If a UPI payment failed but money was debited, save the transaction reference and check the linked bank statement first. Then identify whether it was a person-to-person transfer, a merchant payment or a successful purchase awaiting a refund. The next step depends on that distinction.
“UPI se paise kat gaye, payment failed dikha raha hai” is a problem with a transaction record and its outcome. A second payment may create a second transaction, so organise the first one before deciding what to do next.
Jump to: Payment status · RBI timeline · Complaint checklist · Message template · FAQs.
First separate failed, pending and successful payments
A debit entry proves money left that account; by itself it does not explain the complete settlement or merchant-order outcome. Compare the same transaction's reference, amount and date across the app, bank record and merchant receipt. A balance notification without these details can be difficult to reconcile.
| What you see | What to check | Next useful action |
|---|---|---|
| Pending or processing | Whether the bank has debited and whether the status changes | Keep the reference; follow the official transaction-help process before another attempt |
| Failed and debited | Payment type, bank debit and any reversal entry | Use the failed-payment process and request the applicable reversal status |
| Successful but merchant disputes receipt | Merchant order record and bank confirmation | Ask the merchant to reconcile the payment; raise a bank dispute when appropriate |
| Successful purchase, but you changed your mind | Merchant cancellation and refund terms | Request a purchase refund from the merchant |
| Unrecognised debit or suspected fraud | Transaction details and account access | Report immediately through official bank and cybercrime channels |
Keep each attempt separate. If two payments have two different reference numbers, do not merge their screenshots into one unexplained case. A merchant might refund one successful duplicate while another attempt is still being investigated.
RBI reversal timeline: why T+1 and T+5 are different
The RBI failed-transaction circular covers specified domestic failures. Its UPI rows set the following outer limits, and define T as the transaction's calendar date. Read the RBI circular and annex.
| Covered incident | Outer reversal limit | Delay compensation |
|---|---|---|
| Sender debited; beneficiary not credited for a fund transfer | By T+1, if credit cannot be effected | ₹100 per day beyond T+1 |
| Debited; merchant does not receive transaction confirmation | Within T+5 | ₹100 per day beyond T+5 |
The circular provides automatic compensation for covered delay without requiring a claim. These rows do not create a blanket deadline for every successful purchase refund, user-error transfer or disputed debit. Identify the applicable incident with the bank.
A calendar-date example
For an illustrative transaction on 11 October 2026, T+1 is 12 October and T+5 is 16 October. These are date additions, not one or five business days from when you complained. The transaction type decides which row applies.
For a covered merchant-confirmation failure whose reversal limit is 16 October, a reversal received on 19 October is three calendar days later. At the stated rate, three days × ₹100 = ₹300. This illustrates the arithmetic; ask the bank to establish the relevant incident and actual reversal dates for your case.
Why the app's help page may show a different waiting period
Google Pay's merchant-help page describes processing and failed-payment support in working days. NPCI's portal FAQ also uses working-day wording in its general reply. The table above follows the RBI circular's calendar-date definition for its specified incidents. Keep the app's operational instructions and the regulatory failure classification clear in your complaint.
What to do when the money has not returned
- Open the affected transaction. Use its official help or dispute option and explain the exact debit, status and payment type.
- Keep the complaint reference. Record the submission date and any promised follow-up. An acknowledgment is different from a credited reversal.
- Contact the bank through its official channel. Ask for the transaction outcome, applicable reversal limit and written handling of any qualifying delay.
- Check the bank statement again. Match the reversal with the same amount and reference rather than assuming every incoming credit belongs to this payment.
| Field | Example or instruction |
|---|---|
| Transaction date and amount | 11 October 2026, ₹2,000 — illustrative only |
| Reference shown in the app | Copy the UPI transaction ID / UTR / RRN exactly as displayed |
| Payment type and status | Person transfer or merchant payment; record the exact status |
| Evidence | Debit entry, reversal entry if any, receipt and relevant merchant response |
| Complaint trail | Ticket number, submission date, promised follow-up and written outcome |
Keep a private copy of the relevant bank entries and the merchant's response. Share the documents only through the provider's official complaint process when requested. Do not post statements, account numbers or transaction screenshots in public comments.
Google Pay: find the transaction's help option
Google Pay's official merchant-payment help directs users to transaction history, the affected payment and “Having issues?” to create a support ticket. It also explains statement entries such as UPI-REV or UPI-RET for reversals. Google Pay merchant-payment troubleshooting.
For PhonePe, another UPI app or your bank app, use that provider's official transaction-help route. Menu wording can change. Start from the payment record, because a general account-help request without its reference can lose important context.
NPCI UPI Help and further escalation
The official NPCI UPI Help portal advertises transaction-status and complaint assistance. It asks users to sign in themselves with their bank-linked mobile number and security verification. Available records and actions depend on the service; it should not be treated as an instant refund button.
If the bank's complaint process does not resolve the matter, check the current eligibility and submission requirements on RBI's Complaint Management System. Keep your first complaint, bank reply and evidence together. Do not assume that filing another complaint automatically approves compensation or resolves the transaction.
A concise message you can adapt for official support
This is an original template, not an official form. Replace the brackets privately; keep the facts consistent with your records.
My account was debited [amount] on [date/time] for UPI reference [reference]. The app shows [exact status]. This was [person transfer / merchant payment]. The recipient or merchant reports [observed outcome], and my statement shows [no reversal / reversal details]. Please confirm the transaction outcome and applicable reversal timeline. If a qualifying delay occurred, please assess compensation under the relevant RBI framework. My earlier complaint reference is [reference, if any]. Please provide a written update.
For a merchant dispute, add the order or invoice reference and any written response. If your own statement already shows the reversal, say so. Request an explanation for a remaining mismatch rather than asserting that no refund was received.
Successful payment, wrong recipient or fraud: use the appropriate process
If an order payment succeeded and you later cancelled the purchase, check the merchant's refund policy and refund reference. That is a purchase-refund question, not automatically one of the failures in the timeline table. Google Pay's official help distinguishes successful merchant refunds from failed payments.
If you sent money to the wrong recipient, contact the bank or app promptly with the correct facts. Do not represent a successful user-error transfer as a technical failure. Recovery is not guaranteed, and a new payment does not cancel the first one.
If the debit is unauthorised or you suspect a financial scam, contact the bank immediately and use the National Cybercrime Reporting Portal or 1930. The Ministry of Home Affairs portal lists these reporting channels. Do not wait for an ordinary refund window before reporting suspected fraud.
UPI refund questions
Should I pay again if it says processing?
Google Pay's official help advises against repeating a merchant payment while it is processing. Preserve the first reference and check its outcome. If a second payment is genuinely required, keep both records and confirm how the merchant will handle any duplicate success.
Does “refund processed” mean the money is in my bank?
Verify the actual statement credit and reference. If the provider says a refund was sent but the credit is missing, request the refund reference and use the bank's official tracing or dispute process.
Is every UPI refund due within one day?
No. The table distinguishes two covered failure types, and a successful purchase refund is a separate case. Use the exact incident rather than a universal one-day claim.
Can someone ask for my UPI PIN to refund me?
Do not disclose your PIN, OTP or password to a support caller. PhonePe's official safety guidance says a UPI PIN is not needed to receive money. A request that authorises a payment or mandate is different from receiving a credit.
What if the deduction came from AutoPay?
Identify the mandate and the individual debit separately. Cancelling a future instruction does not automatically reverse an earlier transaction. Read our UPI AutoPay cancellation and troubleshooting guide.
Sources checked 11 October 2026. This independent educational guide is not affiliated with RBI, NPCI or payment apps and does not process complaints or promise recovery.


