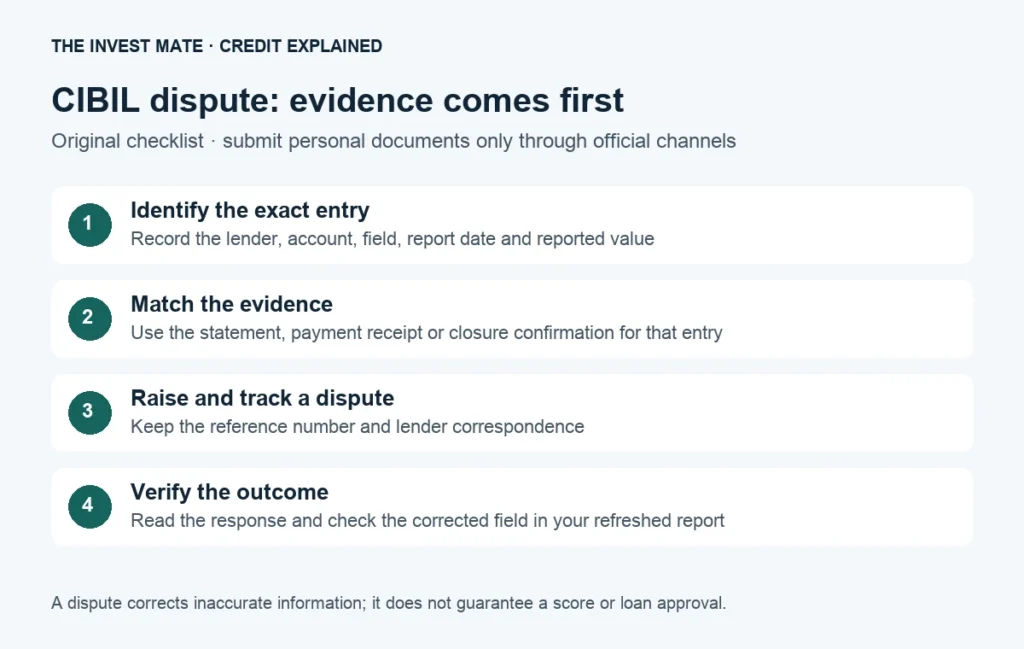
Reviewed 10 October 2026. This guide explains the official dispute route and an original evidence checklist. Do not submit a credit report, PAN, account documents or OTPs to The Invest Mate.
A CIBIL dispute is a request to verify inaccurate information in your credit report. Identify the exact field and supply evidence through official channels. A wrong loan entry, incorrect balance or inaccurate payment entry needs investigation; a low score alone does not establish an error.
Wrong loan, overdue balance or payment: what should you check?
Start with the latest report and your own records. CIBIL's dispute-process guide says closed accounts can remain part of the credit history and an app-based loan may appear under its partner lender's name. Source: CIBIL dispute-process guide. An unfamiliar name needs checking before assuming it is fraudulent.
| Concern | Compare against | Question to resolve |
|---|---|---|
| A loan you do not recognise | Applications, app lending documents and lender identity | Does this account actually belong to you? |
| Wrong balance or overdue amount | Statement, payment receipt and report date | Is the report older than the payment, or is the reported amount incorrect? |
| Closed loan still shown as open | Closure confirmation and the reporting date | Was closure correctly reported? |
| Late-payment entry you believe is wrong | Contractual due date, payment and posting records | Do the records support the requested correction? |
| Unfamiliar lender enquiry | Credit applications and consent records | Which application triggered the enquiry? |
| Incorrect personal details | Accurate identity records and lender updates | Which specific field needs correction? |
For an original example, a report generated before your payment may still display the earlier balance. Record both dates. If the lender acknowledges the payment but a later entry remains wrong, the receipt and written acknowledgement make the concern more specific than “please increase my score”.
How to raise a CIBIL dispute online
CIBIL's official consumer-dispute page specifies reports from the past 60 days, a free dispute service and lender confirmation before information is changed. It gives a 30-day resolution requirement from receipt by CIBIL or the lender. Source: CIBIL consumer dispute resolution.
- Use the official CIBIL route: open the consumer-dispute page above and follow its MyCIBIL login or new-user route yourself.
- Locate the report entry: note the lender, relevant account or enquiry and the exact field you believe is inaccurate.
- Select the relevant dispute section: use account, profile or enquiry information, as appropriate.
- Explain the correction: state the reported value, the requested value and the supporting reason accurately.
- Provide requested evidence through the official form: check that attachments match the entry and follow the displayed requirements.
- Keep the acknowledgement: save the dispute ID, filing date, original description and any lender reference.
The portal's labels and document requirements may change. Follow what the official form currently asks for. Do not use a company-credit-report form for an individual consumer issue.
Suspected error → evidence → official dispute → lender verification → response → refreshed report check
A factual CIBIL complaint template
Use the following original template as a drafting aid. Replace placeholders with your own accurate facts and use the official submission channel. Keep sensitive identifiers out of public comments or social posts.
Subject: Request to verify an incorrect credit-report entry
My report dated [date] shows [lender/account reference] with [field] recorded as [reported value]. I believe this is inaccurate because [brief factual reason]. My supporting records are [statement/receipt/closure confirmation and dates].
Please verify the entry with the reporting lender, explain the result and correct the field if the evidence supports it. Please provide a complaint reference and confirm the next steps. My earlier reference, if applicable, is [reference].
A useful complaint names the field and evidence. Avoid claiming that every negative entry is wrong, requesting a target score or alleging fraud without checking the documents. If you genuinely did not authorise an account, clearly state that ownership concern.
How to track CIBIL dispute status and verify a correction
Use the dispute reference when following up. CIBIL's contact FAQs describe tracking through MyCIBIL and selecting the relevant report section for a dispute. Source: CIBIL contact FAQs. Maintain a single chronology of replies from the bureau and lender.
| Record | What to write |
|---|---|
| Initial filing | Date, channel, dispute ID and requested correction |
| Lender response | Date, reference and whether the disputed fact was confirmed |
| CIBIL response | Date, explanation, resolution and any next step |
| Refreshed report | Report date, field value and whether it matches the response |
| Unresolved point | The precise remaining discrepancy and relevant evidence |
For example, if your concern was an incorrect ₹8,000 overdue balance, verify that specific account and field after the response. Looking only at the headline score cannot establish whether the error was corrected. Keep the original and refreshed reports privately for comparison.
What if the dispute is delayed or the result is unsatisfactory?
CIBIL's compensation framework describes ₹100 per calendar day for qualifying dispute-resolution delays beyond 30 calendar days. It covers delayed resolution, rather than every service problem or dissatisfaction with an outcome. Read its conditions and use the dispute dashboard for the applicable calculation. Source: CIBIL compensation framework.
Request the explanation and use the official complaints/escalation route when needed. CIBIL's grievance policy describes escalation and the RBI Ombudsman route for eligible complaints. Source: CIBIL grievance redressal policy. Eligibility and the applicable process must be checked for your case; this guide does not file a complaint for you.
A dispute about inaccurate information and a repayment difficulty require different actions. Continue to address actual obligations with the lender while the information issue is examined. For ongoing credit habits, read our CIBIL score improvement guide.
Frequently asked questions
Can CIBIL remove a loan that is not mine?
Raise a specific ownership dispute with accurate evidence. The entry is verified with the lender; the investigation determines whether a correction is justified.
Is raising a CIBIL dispute free?
CIBIL describes its dispute-resolution service as free. A paid intermediary is not required for that official process.
Should every closed loan disappear from my report?
No. Closed accounts can remain in the history. Check whether ownership, status, balance and repayment information are accurate.
Does a dispute guarantee my score will reach 700 or 750?
No. The task is accurate reporting. The score reflects the wider credit history, and lender approval is a separate decision.
Should I upload my report here for help?
No. Use CIBIL's or your lender's official channel for personal documents. The Invest Mate provides general educational guidance.
Sources reviewed 10 October 2026. Checklists, tables, flow diagram and complaint template are independently written. The Invest Mate is not affiliated with TransUnion CIBIL and does not sell credit repair.


